Good credit can make many parts of your financial life easier.
Whether you are applying for a credit card, financing a vehicle, renting a home, or preparing for future financial goals, your credit history can influence the options available to you.
The good news is that building and maintaining good credit does not require complicated strategies.
It is mostly about developing consistent habits, understanding how credit works, and managing borrowed money responsibly.
For people who are just starting to establish credit, the process may seem confusing. For those who already have a credit history, maintaining a strong profile requires ongoing attention. In both cases, small and consistent decisions can make a meaningful difference over time.
Understand What Credit Means
Before working on your credit, it helps to understand what lenders generally look at when evaluating your creditworthiness. Your credit history provides information about how you have handled borrowed money in the past. Depending on the scoring system and lender, factors can include payment history, amounts owed, length of credit history, types of credit accounts, and applications for new credit.
A credit score is different from your complete credit report. A score is a numerical summary calculated from information in a credit report, while the report contains details about your accounts and payment activity. Different scoring models can produce different scores, so it is useful to focus on healthy financial behavior rather than trying to achieve a particular number overnight.
Start With Manageable Credit
If you have little or no credit history, starting small can be a practical approach. A basic credit card or another appropriate credit product may help you establish a record of responsible borrowing. The goal is not to borrow as much as possible. Instead, use credit only for purchases you can reasonably afford to repay.
For example, you might use a credit card for a few regular expenses and then pay the balance according to the account terms. Using credit this way can help you become comfortable with borrowing while avoiding unnecessary debt.
It is also important to read the terms before opening an account. Pay attention to interest rates, fees, payment dates, and other conditions. Choosing an account that fits your financial situation can make responsible credit management easier.
Make Payments on Time
Payment history is an important part of many credit scoring models, which makes paying bills on time one of the most valuable credit habits you can develop.
A missed payment can potentially hurt your credit history, depending on factors such as how late the payment is and how the creditor reports it. Repeated late payments can create additional problems and make it harder to demonstrate responsible financial behavior.
One simple way to stay organized is to set reminders before your due dates. Some people also use automatic payments for at least the required amount, while making additional payments manually when appropriate. However, automatic payments should be monitored to make sure there is enough money in the linked account.
Keep Credit Card Balances Under Control
Using a credit card does not mean you need to carry a balance from month to month. If your card agreement allows it and you can afford to do so, paying the statement balance in full can help you avoid interest charges on purchases.
Another important concept is credit utilization, which generally refers to how much of your available revolving credit you are using. A high balance compared with your credit limit can affect some credit scores. Keeping balances at a manageable level can therefore be helpful.
Rather than treating your credit limit as available spending money, think of it as a borrowing limit that should be used carefully. Your personal budget, not your credit limit, should determine how much you spend.
Create a Realistic Budget
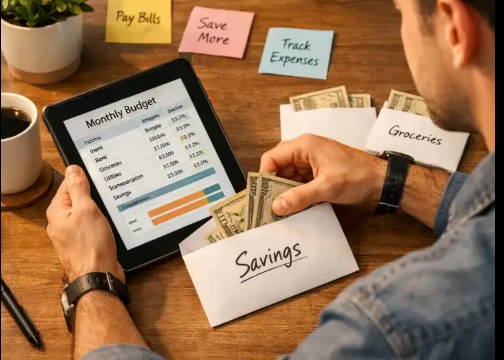
Good credit management starts with good money management. A realistic budget can help you understand how much money comes in, where it goes, and how much you can comfortably allocate toward debt payments and savings.
Start by reviewing your regular income and essential expenses. Then consider discretionary spending, existing debt payments, savings goals, and occasional expenses. A budget does not have to be complicated. Even a simple monthly plan can make it easier to avoid relying on credit for expenses you cannot comfortably afford.
When your spending is aligned with your income, you are generally in a better position to make payments on time and keep borrowing under control.
Avoid Applying for Too Much Credit at Once
Credit can be useful, but opening several accounts within a short period may not always be beneficial. Applications for certain types of credit can result in hard inquiries, which may affect credit scores for a period of time.
More importantly, opening multiple accounts can make it harder to keep track of balances, payment dates, and account terms. Before applying for a new account, consider whether you genuinely need it and whether it fits your overall financial plan.
Shopping around for certain loans may be treated differently by some scoring models, particularly when applications occur within a defined period, but the exact treatment can vary. Understanding the terms and asking questions before applying can help you make informed decisions.
Keep Older Accounts in Mind
The length of your credit history can be another factor considered by some credit scoring models. As a result, maintaining older accounts responsibly may sometimes be useful.
However, keeping an account open is not automatically the right choice in every situation. An account with expensive fees or terms that no longer fit your needs may deserve a closer review. Consider the costs, benefits, and your overall financial situation before making changes.
The main objective is to maintain accounts responsibly rather than keeping accounts open simply to increase the age of your credit history.
Check Your Credit Reports
Reviewing your credit reports can help you understand what lenders may see and identify information that appears incorrect. Depending on where you live, you may have access to credit reports from one or more credit reporting agencies.
When reviewing a report, look for unfamiliar accounts, incorrect personal information, inaccurate payment information, or other details that do not appear to belong to you. If you find an error, follow the appropriate dispute process provided by the credit reporting agency and the company that supplied the information.
Regularly reviewing your credit information can also help you become more aware of your overall financial picture.
Manage Debt Carefully
Building good credit does not mean taking on more debt. In fact, responsible debt management is an important part of a healthy financial plan.
If you already have several balances, consider creating a repayment strategy that fits your budget. You might prioritize the balance with the highest interest rate or use another approach that helps you stay motivated and consistent.
Whatever strategy you choose, avoid taking on new debt simply to manage existing debt without understanding the costs. If your debt payments are becoming difficult to manage, contacting creditors early and exploring available options may be better than waiting until the situation becomes more challenging.
Be Careful With Co-Signing and Joint Accounts
Helping someone obtain credit by co-signing may seem generous, but it can create financial responsibility for you. Depending on the agreement, you may become responsible for the debt if the other person does not make the required payments.
Before co-signing, make sure you fully understand the potential consequences. A missed payment could affect your own credit history, and the debt may influence your ability to qualify for other financial products.
Joint accounts can also create shared financial responsibilities, so they should be approached thoughtfully.
Give Your Credit Time
Building good credit is a long-term process. There is no reliable shortcut that can instantly create a strong credit history. Responsible habits become more valuable when they are repeated consistently over months and years.
If your credit history is not where you want it to be, do not become discouraged. Start with the areas you can control. Make payments on time, manage balances carefully, review your credit information, and avoid unnecessary borrowing.
Over time, these habits can create a stronger financial foundation.
Final Thoughts
Good credit is less about finding a perfect financial trick and more about making responsible decisions consistently. Paying bills on time, keeping debt manageable, understanding account terms, monitoring credit reports, and maintaining a realistic budget can all contribute to healthier credit habits.
Your credit is one part of your overall financial picture, not a measure of your personal worth. Focus on building habits that support your long-term goals rather than worrying about achieving a particular score immediately. With patience, organization, and responsible borrowing, you can gradually build a credit history that supports greater financial flexibility and confidence.