Managing money well is an important life skill that can make everyday decisions feel more comfortable and future goals easier to reach.
You do not need a high income or advanced financial knowledge to begin.
Good money management starts with understanding where your money goes, making thoughtful choices, and creating habits that support your priorities.
For beginners, financial management can sometimes seem complicated because there are many terms, products, and opinions to consider. The good news is that the basics are quite simple. By taking a few practical steps and staying consistent, you can build a healthier relationship with your money over time.
Understand Your Current Financial Picture
The first step in managing money is knowing what you have and how you use it. Start by looking at your regular income and everyday expenses. Your income may come from employment, freelance work, a business, or other reliable sources.
Next, consider where your money goes each month. Common expenses include housing, food, transportation, utilities, communication services, insurance, education, entertainment, and personal purchases.
You do not need to make the process complicated. Reviewing several weeks or a full month of transactions can help you identify spending patterns. You may discover that some expenses are essential while others are flexible. This information gives you a clearer starting point for making decisions.
Create a Simple Spending Plan
A spending plan helps you decide how your money should be used before the month gets too far along. Instead of wondering where your income went, you can give different amounts a purpose.
Begin with essential expenses. These are costs that are generally necessary for daily life, such as housing, food, transportation, and basic household needs. Then consider financial priorities, including savings and debt payments. Finally, leave room for flexible spending and activities you enjoy.
A good spending plan should be realistic. If it is too restrictive, it may become difficult to maintain. Give yourself reasonable flexibility while keeping your larger financial priorities in view.
Make Saving a Regular Habit
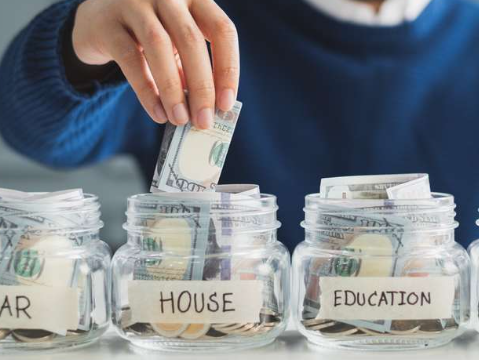
Saving is one of the most useful habits you can develop. Even a modest amount saved consistently can become meaningful over time.
Consider treating savings as part of your regular financial routine rather than something you do only when money is left over. You might choose a specific amount or percentage of your income and set it aside regularly.
An emergency fund can be a particularly useful savings goal. It can provide a financial cushion for unexpected costs such as necessary repairs, temporary income changes, or other unplanned expenses. The appropriate amount depends on your circumstances, so focus first on building a manageable reserve and increase it gradually as your finances allow.
Keeping savings in a separate account can also make it easier to distinguish money intended for future needs from money available for everyday spending.
Be Thoughtful About Debt
Debt can be a useful financial tool in some circumstances, but it is important to understand the cost and repayment requirements before borrowing.
If you already have debt, review the balances, interest rates, minimum payments, and repayment schedules. Having this information organized can make your situation easier to understand.
Paying required amounts on time is an important part of responsible debt management. When possible, you can also consider directing additional money toward higher-cost debt while continuing to meet other obligations.
Before taking on new debt, ask yourself whether the payment comfortably fits within your spending plan. Understanding the full cost of borrowing can help you make more informed decisions.
Separate Needs From Wants
One of the simplest money-management skills is learning to distinguish between needs and wants. Needs are expenses that support basic living and important responsibilities. Wants are purchases that may improve comfort or enjoyment but are not essential.
This does not mean you should avoid everything you enjoy. A balanced financial life can include entertainment, hobbies, dining out, travel, and other personal choices. The key is making those purchases intentionally instead of allowing them to interfere with important financial priorities.
Before making a nonessential purchase, consider whether it fits your current spending plan and whether you will still feel comfortable with the decision afterward.
Set Short-Term and Long-Term Goals
Financial goals give your money a sense of direction. Your goals might include building savings, preparing for a major purchase, reducing debt, developing professional skills, or preparing for future financial needs.
It can help to separate goals into different time periods. Short-term goals may take several months, while longer-term goals may require several years.
Make your goals specific and measurable when possible. Instead of simply saying that you want to save more, decide how much you would like to save and when you would like to reach that target. Reviewing your progress regularly can help you stay motivated and adjust your approach when circumstances change.
Use Simple Tools to Stay Organized
You do not need complicated software to manage your money. A basic spreadsheet, budgeting application, banking tools, or even a simple written record can be enough.
Choose a system that you are comfortable using consistently. The most effective method is usually the one that makes it easy for you to review income, expenses, savings, and financial commitments.
Checking your accounts regularly can also help you notice unusual transactions, upcoming payments, or areas where your spending may have changed.
Protect Your Financial Information
Good money management also includes protecting your financial accounts and personal information. Use strong, unique passwords and enable additional security features when available.
Be cautious when receiving unexpected messages or requests for financial information. Before clicking links or providing account details, verify that the request comes from a legitimate source.
Reviewing account activity periodically can help you identify transactions that you do not recognize. Taking small security precautions can reduce unnecessary financial risks.
Keep Learning Over Time
Financial knowledge develops gradually. You do not have to understand every financial concept before getting started. Begin with the basics and learn more as your needs change.
You may eventually want to learn about topics such as retirement planning, investing, insurance, taxes, or different types of financial accounts. When researching these subjects, consider information from reputable sources and understand that financial decisions can depend on individual circumstances.
It is also wise to be cautious about promises of quick or guaranteed financial results. A thoughtful approach focuses on understanding risks, costs, and realistic expectations.
Review and Adjust Your Plan
Your financial situation will not remain exactly the same forever. Income can change, household expenses can increase, and personal priorities may evolve.
For this reason, money management should be viewed as an ongoing process rather than a one-time task. Set aside some time each month to review your spending, savings, goals, and upcoming expenses.
If something is not working, make a reasonable adjustment rather than giving up completely. A spending plan that changes with your circumstances can be much more useful than one that is difficult to maintain.
Building Confidence With Money
Managing money is less about being perfect and more about developing consistent habits. Understanding your financial position, planning your spending, saving regularly, handling debt carefully, and setting meaningful goals can create a strong foundation for the future.
The most important step for a beginner is simply to start. You can begin by reviewing your recent expenses, identifying one savings goal, and creating a spending plan that reflects your real life.
Over time, these small actions can become natural habits. With patience and regular attention, you can gain greater confidence in your financial decisions and create a more organized approach to managing money.