Managing money does not have to feel complicated.
For many people, everyday finance is less about making perfect decisions and more about developing practical habits that make life easier.
Knowing where your money goes, planning for regular expenses, preparing for unexpected costs, and making thoughtful choices can create a stronger financial foundation over time.
This Everyday Finance Guide offers a straightforward approach to personal money management. It is designed for ordinary financial situations, whether you are organizing your monthly budget, trying to build savings, or simply looking for a clearer way to manage day-to-day spending.
Start With a Clear Picture of Your Money
A useful first step is understanding your financial routine. Look at your regular income and compare it with your typical expenses. Include essentials such as housing, food, transportation, utilities, insurance, and other recurring commitments. It can also help to consider flexible spending, including entertainment, dining, shopping, and subscriptions.
The goal is not to judge every purchase. Instead, you are creating a realistic picture of your financial habits. Once you know how your money is being used, it becomes easier to decide what deserves attention.
A simple monthly review can reveal opportunities to reduce unnecessary costs or redirect money toward priorities that matter more to you.
Build a Practical Spending Plan
A budget works best when it reflects real life. Extremely restrictive plans can be difficult to maintain, especially when unexpected expenses appear. A more practical approach is to give your money different purposes while leaving room for ordinary enjoyment and changing circumstances.
Consider separating essential expenses, personal spending, savings, and financial obligations. The exact amounts will vary from person to person. There is no single budgeting formula that works for everyone.
You can also review your plan regularly instead of treating it as a permanent rule. Income, household needs, prices, and personal goals can change. A flexible budget can change with them.
Make Saving a Regular Habit
Saving can be easier when it becomes part of your normal financial routine rather than something you attempt only when extra money happens to be available.
Even modest, consistent contributions can help create a financial cushion. You might begin by choosing a realistic amount that fits your circumstances and then gradually increase it when your budget allows.
An emergency fund can be particularly useful because unexpected costs are a normal part of life. A repair, replacement, urgent travel expense, or temporary income disruption can be easier to manage when some money has already been set aside.
The most important consideration is sustainability. A savings habit that fits comfortably into your financial life is often more useful than an ambitious target that becomes difficult to maintain.
Be Thoughtful About Credit and Borrowing
Credit can be a useful financial tool, but borrowing creates an obligation that should be considered carefully. Before taking on new debt, look beyond the advertised payment and understand the broader cost, including interest, fees, repayment periods, and other applicable terms.
For existing balances, keeping track of due dates can help avoid unnecessary complications. Paying attention to account statements and reviewing transactions regularly can also help you spot mistakes or charges you do not recognize.
If you are considering a financial product, read its terms carefully and compare options before making a decision. Personal financial circumstances differ, so a product that works well for one person may not be appropriate for another.
Protect Your Financial Information
Everyday finance also includes keeping financial accounts and personal information secure. Use strong, unique passwords where possible and enable additional security features offered by your financial institutions.
Be cautious with unexpected messages asking for account details, passwords, verification codes, or payments. If something seems unusual, contact the relevant organization through a trusted channel rather than relying on contact information supplied in a suspicious message.
Regularly reviewing account activity can provide another layer of awareness. Early attention to an unfamiliar transaction may make it easier to investigate a potential problem.
Prepare for Future Goals
Financial planning is not limited to monthly bills. It can also help you think about what you want in the future.
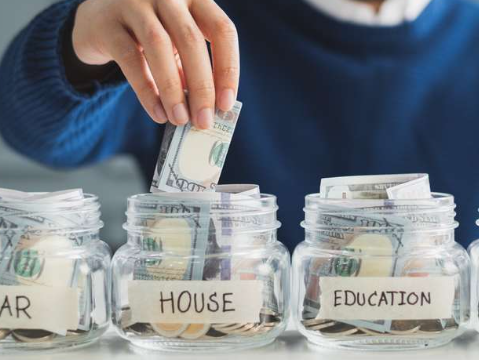
Your goals might include building a larger savings reserve, preparing for education, purchasing a home, starting a business, traveling, or simply creating more financial flexibility. Different goals may require different timelines and strategies.
Writing down a goal can make it more concrete. Instead of saying you want to save more, consider identifying what you are saving for, approximately how much you may need, and when you would like to reach the goal. You can then review your progress periodically and adjust your approach when circumstances change.
Review Your Finances Regularly
You do not need to spend hours managing money every day. A short financial check-in once a week or once a month can be enough to keep important details visible.
Review recent spending, upcoming bills, savings progress, and any changes to your income or expenses. This routine can help prevent small issues from becoming larger surprises.
It is also useful to revisit recurring services and subscriptions occasionally. If you no longer use something, canceling it may free up money for a more meaningful purpose.
Keep Financial Decisions Personal
Personal finance is exactly that: personal. Household circumstances, income, responsibilities, goals, and priorities differ widely.
Comparing your financial life with someone else’s can sometimes create unnecessary pressure. A healthier approach is to measure progress against your own goals. Improving your financial habits gradually can be more valuable than trying to follow a strategy simply because it is popular.
When a decision has significant financial consequences, consider seeking qualified professional guidance that takes your individual circumstances into account. General financial information can help with education, but it should not be treated as individualized financial, tax, legal, or investment advice.
A Calm Approach Can Make a Difference
Good money management does not require perfection. It is built through awareness, consistency, and thoughtful decisions.
Start by understanding your income and expenses. Create a realistic spending plan, make saving a regular habit, approach borrowing carefully, protect your financial information, and review your progress from time to time. These simple practices can make everyday financial decisions feel more manageable.
Most importantly, give yourself room to learn. Financial habits can improve gradually, and a small positive change repeated over many months can have a meaningful effect. The goal is not to make money management stressful. It is to create a system that helps you feel more informed, prepared, and confident about your financial choices.