Managing money effectively is an important part of building a more comfortable and organized life.
Practical finance is not only about earning more or investing aggressively.
It is also about understanding everyday financial decisions, creating healthy habits, planning ahead, and using available resources wisely.
With a simple and consistent approach, people can make their finances easier to manage and feel more confident about their financial direction.
One useful area of practical finance is creating a realistic household budget. A budget provides a clear picture of how money comes in and where it goes each month. Instead of making complicated calculations, individuals can begin by listing regular income and essential expenses such as housing, utilities, food, transportation, and other recurring costs. Once these expenses are understood, it becomes easier to identify flexible spending and decide where adjustments may be helpful.
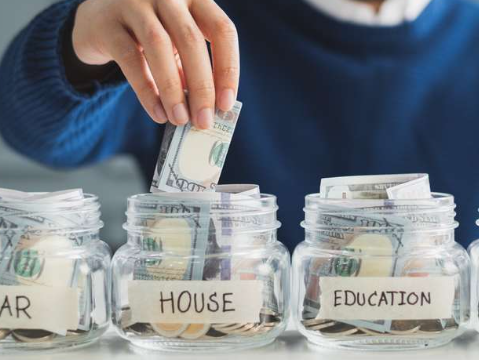
Saving money is another important financial habit. Even small, regular contributions can become meaningful over time. A savings plan can be designed around personal circumstances, with an emphasis on consistency rather than perfection. Setting aside money after receiving income can make saving a normal part of the monthly routine. Separate savings goals can also help people prepare for planned purchases, annual expenses, or unexpected situations.
An emergency fund can provide additional financial flexibility. Life can bring unexpected costs, including home repairs, vehicle expenses, or changes in income. Having accessible savings may reduce the need to rely on credit when an unplanned expense occurs. The appropriate amount depends on individual circumstances, income stability, and regular expenses, so people can build their emergency savings gradually according to what works for them.
Understanding everyday spending is equally valuable. Small purchases may seem insignificant individually, but repeated spending can have a noticeable effect on a monthly budget. Reviewing bank statements and transaction histories can help reveal spending patterns. This process is not about avoiding every enjoyable purchase. Instead, it can help individuals make deliberate choices and ensure that their spending reflects their priorities.
Debt management is another practical finance topic worth understanding. Different types of debt can have different terms, interest rates, and repayment requirements. Keeping track of balances and payment dates can help prevent missed payments and unnecessary fees. People who are managing multiple debts may benefit from creating a clear repayment strategy that fits their income and overall financial situation.
Credit can also play a role in personal financial planning. Responsible credit use involves understanding payment obligations, interest charges, and the terms associated with borrowing. Before taking on new debt, it can be helpful to consider whether the payment fits comfortably within the existing budget. Reading agreements carefully and comparing available options can support more informed decisions.
Financial planning should also include longer-term goals. These may include purchasing a home, starting a business, preparing for education expenses, or building retirement savings. Long-term goals can feel easier to manage when they are divided into smaller steps. Setting a target, estimating the required amount, and reviewing progress periodically can turn a broad goal into a practical financial plan.
Learning basic investing concepts can complement long-term planning. Investing involves risk, and different investments have different characteristics. Before making investment decisions, individuals should understand concepts such as diversification, time horizon, fees, and risk tolerance. A thoughtful approach focuses on learning and aligning financial choices with personal goals rather than following short-term market excitement.
Protecting financial information is another increasingly important topic. People should be careful when sharing account details, passwords, payment information, and other sensitive data. Using strong passwords, enabling available security features, and reviewing account activity regularly can help maintain better financial security. Staying cautious with unexpected messages and unfamiliar payment requests is also a useful everyday habit.
Financial organization can make many of these practices easier. Keeping important financial documents in a secure location, monitoring recurring payments, and reviewing accounts regularly can reduce confusion. Some people prefer digital tools, while others use simple spreadsheets or written records. The best system is one that is easy to maintain and provides a clear view of important financial information.
Good financial habits do not require a perfect income or complicated strategies. Practical finance is largely about making informed choices repeatedly. Creating a budget, building savings, managing debt carefully, understanding credit, planning for future goals, and protecting financial information can all contribute to greater financial stability.
Most importantly, financial progress takes time. Everyone has different responsibilities, income levels, goals, and priorities. Comparing personal finances with someone else’s situation may not provide a useful measure of success. A more constructive approach is to focus on personal progress and make reasonable improvements over time.
Practical finance is ultimately about creating a system that supports everyday life and future goals. By understanding basic financial principles and developing sustainable habits, individuals can make money management less stressful and more purposeful. Small steps taken consistently can create a stronger foundation for future financial decisions while allowing people to enjoy the present responsibly.