Personal finance is an important part of everyday life.
The way we manage income, spending, saving, and financial goals can influence the opportunities available to us in the future.
While money management may sometimes seem complicated, it does not have to be overwhelming.
Learning a few practical principles and applying them consistently can make financial decisions feel more organized and manageable.
Personal finance covers many areas, from creating a household budget to preparing for future goals. It also includes building healthy spending habits, understanding financial products, managing debt responsibly, and preparing for unexpected expenses. By exploring these topics at your own pace, you can develop a clearer understanding of how different financial choices fit into your personal circumstances.
Understanding Your Financial Picture
A useful starting point for personal finance is understanding where your money currently goes. Reviewing your regular income and expenses can provide a simple overview of your financial situation. This may include housing costs, transportation, groceries, utilities, subscriptions, entertainment, and other everyday expenses.
Knowing your spending patterns can help you identify areas where your money is being used intentionally and areas where you may want to make adjustments. The purpose is not to eliminate everything you enjoy. Instead, it is about creating a balance between current needs and future priorities.
A clear financial picture can also make it easier to set realistic goals. When you understand your available resources, you can make plans that are more practical and easier to maintain.
Building a Practical Budget
A budget is a simple framework for deciding how income will be allocated. It can help organize essential expenses, personal spending, savings, and other financial priorities.
There is no single budgeting method that works for everyone. Some people prefer detailed monthly categories, while others use a simpler approach based on broad spending groups. The most useful system is usually one that is easy to understand and realistic enough to follow regularly.
A budget should also have some flexibility. Unexpected expenses can occur, and priorities can change. Reviewing your budget periodically allows you to make adjustments without feeling that a temporary change means the entire plan has failed.
Developing Healthy Spending Habits
Spending is a normal part of life, and responsible money management does not mean avoiding purchases altogether. The goal is to make thoughtful choices that support both present needs and longer-term objectives.
Before making a purchase, it can be helpful to consider whether it is necessary, useful, or simply an impulse. Waiting before making nonessential purchases can sometimes provide enough time to decide whether the expense truly fits your priorities.
Comparing prices, reviewing recurring subscriptions, and looking for better value can also make everyday spending more efficient. Small improvements may not seem significant individually, but consistent habits can have a meaningful effect over time.
Creating an Emergency Fund
Unexpected costs are one of the most common challenges in personal finance. Car repairs, household maintenance, temporary income changes, or other surprises can place pressure on a household budget.
An emergency fund can provide a financial cushion for situations that are difficult to predict. The appropriate amount depends on individual circumstances, income stability, essential expenses, and personal responsibilities.
Building an emergency fund does not necessarily require large contributions at once. Setting aside a manageable amount regularly can gradually create a useful reserve. Keeping these funds separate from everyday spending may also make it easier to preserve them for genuine unexpected needs.
Managing Debt Responsibly
Debt can be part of many people’s financial lives. Loans and credit products may help people manage large expenses, but borrowing also creates future payment obligations.
Understanding the terms of a debt is an important step. Interest rates, payment schedules, fees, and repayment periods can all affect the overall cost. Keeping track of required payments can help prevent missed deadlines and unnecessary charges.
When managing multiple debts, it can be useful to create a clear repayment strategy based on personal circumstances. Paying attention to high-cost debt while continuing to meet required payments on other obligations can be one approach. If debt becomes difficult to manage, speaking with a qualified financial professional may provide additional guidance.
Saving for Short-Term and Long-Term Goals
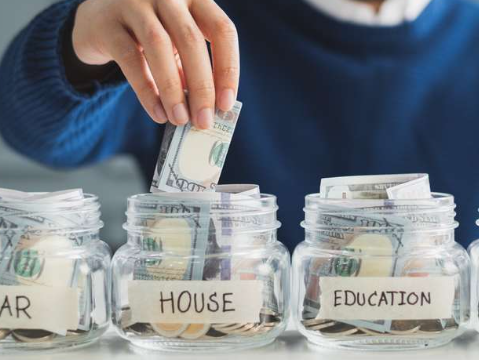
Saving becomes easier when it has a clear purpose. Short-term goals might include a planned purchase, a vacation, education expenses, or a household project. Long-term goals may include retirement, homeownership, or other major life plans.
Separating goals can make progress easier to track. Instead of thinking about saving as one large task, you can consider each objective individually and determine what amount may be reasonable to set aside regularly.
Automating savings through a bank account, where appropriate, can also help create consistency. Even modest contributions can become meaningful when maintained over an extended period.
Learning About Investing
Investing is another important personal finance topic, particularly for people thinking about long-term financial goals. Investments can include different types of assets, and each option has its own characteristics, potential benefits, and risks.
Before investing, it is helpful to understand concepts such as diversification, time horizon, fees, and risk tolerance. No investment is guaranteed to produce a particular result, and past performance does not ensure future outcomes.
People who are new to investing may benefit from learning the basics before making decisions. Reliable educational resources and guidance from qualified professionals can help individuals better understand options that may be appropriate for their circumstances.
Planning for the Future
Financial planning is not only about managing today’s expenses. It also involves considering what you may want your financial life to look like in the years ahead.
Future planning can include retirement preparation, education costs, housing decisions, insurance considerations, and other major financial priorities. The earlier these subjects are considered, the more time there may be to adjust the plan as circumstances change.
Life does not always follow a predictable path. Income, family responsibilities, career plans, and personal priorities can change. A good financial plan should therefore be reviewed periodically rather than treated as a permanent set of rules.
Improving Financial Knowledge
Financial literacy can make everyday decisions easier. Understanding basic terms and concepts can help people compare options, ask better questions, and recognize when additional information may be needed.
Learning does not have to happen all at once. You might begin with budgeting, then explore saving, debt management, investing, and retirement planning as your knowledge grows. Trusted financial institutions, government resources, educational organizations, and qualified professionals can provide useful information.
It is also important to be cautious with financial claims that promise quick or guaranteed results. Personal finance generally rewards patience, consistency, and informed decision-making rather than shortcuts.
Making Personal Finance a Regular Habit
One of the most effective ways to improve personal finances is to make money management part of a regular routine. A brief financial review each week or month can help you stay aware of spending, upcoming expenses, savings progress, and changing priorities.
The objective is not perfection. Financial circumstances can change, and occasional mistakes are part of learning. What matters is recognizing what happened, making reasonable adjustments, and continuing forward.
Personal finance is ultimately about creating a system that supports your life. By understanding your financial position, spending thoughtfully, saving consistently, managing obligations responsibly, and learning about long-term planning, you can build stronger financial habits over time.
There is no universal formula for managing money. Everyone has different goals, resources, responsibilities, and priorities. The most valuable approach is one that is realistic, adaptable, and based on a clear understanding of your own circumstances. With steady attention and informed choices, personal finance can become less stressful and more purposeful, helping you work toward a more organized and confident financial future.