Smart financial planning is not about becoming wealthy overnight or making complicated investment decisions.
It is about understanding where your money goes, setting realistic goals, and making thoughtful choices that support your life today while preparing you for tomorrow.
A well-designed financial plan can provide greater clarity, reduce unnecessary stress, and help you feel more confident when making everyday money decisions.
The foundation of smart financial planning begins with awareness. Before deciding how much to save or invest, it helps to understand your current financial situation. Take some time to review your income, regular expenses, savings, debts, and financial commitments. This simple overview gives you a clearer picture of your financial habits. You may discover areas where money is being used efficiently as well as expenses that could be adjusted.
Understanding your cash flow is particularly important. Cash flow simply describes the money coming into your household compared with the money going out. When income consistently exceeds expenses, you have an opportunity to save, prepare for future goals, or manage existing obligations more comfortably. When expenses regularly exceed income, reviewing spending patterns can help identify practical adjustments.
Creating a realistic spending plan is another essential part of financial planning. A budget does not need to feel restrictive. Instead, it can serve as a guide that helps you decide where your money should go before it is spent. Start with essential costs such as housing, utilities, transportation, groceries, insurance, and other regular commitments. Then consider flexible spending, savings, personal goals, and occasional expenses.
A useful spending plan should reflect your actual lifestyle rather than an idealized version of it. If a budget is too strict, it can become difficult to maintain. Allowing reasonable room for entertainment, hobbies, meals out, or other personal priorities can make the plan more sustainable. The goal is not to eliminate every enjoyable expense but to make sure those expenses fit comfortably within your overall financial picture.
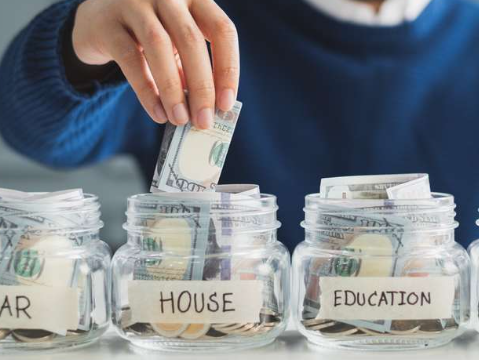
Setting financial goals gives your planning process direction. Goals can be short term, such as building savings for an upcoming purchase, or longer term, such as preparing for retirement or buying a home. Whatever the goal, it helps to make it specific and measurable. Instead of simply deciding to save more money, determine how much you want to save and when you would like to reach that target.
An emergency fund is another important element of a strong financial foundation. Unexpected expenses can occur at any time, from a major household repair to an unplanned personal expense. Having accessible savings can provide a financial cushion and reduce the need to rely on high-cost borrowing when something unexpected happens. The appropriate amount varies from person to person, so consider your income stability, regular expenses, and personal circumstances when determining a suitable target.
Managing debt is also an important part of smart planning. Not all debt has the same characteristics, so understanding interest rates, payment schedules, and outstanding balances can help you make informed decisions. Keeping required payments organized and avoiding unnecessary new debt can gradually improve financial flexibility. If you have multiple obligations, reviewing them carefully can help you determine which ones deserve greater attention.
Saving consistently can make financial progress easier over time. Even when the amount saved each month is modest, establishing a regular habit can be valuable. Automatic transfers can make saving more convenient because the money is set aside before it is easily spent elsewhere. As your income or circumstances change, you can review the amount and adjust it when appropriate.
Once basic savings and everyday finances are organized, long-term investing may become part of your financial plan. Investing involves risk, and different investments can behave differently depending on market conditions. Before investing, it is important to understand your goals, time horizon, risk tolerance, fees, and the nature of the investment itself. Diversification can help spread exposure across different assets, but it cannot guarantee that you will avoid losses.
Retirement planning deserves attention as well. The earlier you begin thinking about long-term financial needs, the more time you may have to build resources for the future. Consider how much you may need later in life and what sources of income may be available. Workplace retirement plans, personal savings, and other appropriate investment accounts may each play a role depending on your circumstances and local rules.
Financial planning should also include protection against major risks. Insurance can help protect your finances from certain unexpected events, although the right coverage depends on individual needs. Reviewing important financial documents, beneficiaries, and household arrangements periodically can also help keep your financial plan aligned with your current circumstances.
Another fundamental principle is to separate financial decisions from short-term emotions whenever possible. Markets may rise and fall, unexpected expenses may appear, and personal priorities can change. Making decisions based solely on fear or excitement can sometimes lead to choices that do not support long-term objectives. A thoughtful plan provides a framework that can help you remain focused when circumstances change.
Regular reviews are essential because financial plans are not permanent documents. Income, expenses, family responsibilities, career plans, and personal goals can all change. A review every few months or at major life milestones can help you identify what is working and what needs adjustment. Small changes made consistently can have a meaningful effect over time.
Technology can make financial organization easier as well. Banking applications, spreadsheets, budgeting tools, and automated savings features can help you monitor accounts and stay aware of spending patterns. However, technology should support your decisions rather than replace them. Take time to understand financial products and check information carefully before making important commitments.
Smart financial planning ultimately comes down to creating a system that is realistic, flexible, and aligned with your priorities. You do not need to have a perfect financial situation before getting started. You can begin by understanding your current position, organizing your spending, building savings, managing obligations, and setting meaningful goals.
The most valuable part of financial planning is consistency. A single good financial decision may help for a short time, but a collection of sensible habits can create stronger results over the years. By reviewing your finances regularly and making adjustments when necessary, you can build greater confidence and create more room for the opportunities and responsibilities that life may bring.
Smart financial planning is therefore less about predicting the future and more about preparing for it. With a clear understanding of your money, realistic goals, disciplined habits, and a willingness to adapt, you can create a financial approach that supports both present needs and future ambitions. The process can begin with a few simple decisions today and gradually develop into a stronger financial foundation for the years ahead.