Achieving financial confidence is a gradual process that begins with understanding your money and making thoughtful decisions about how you use it.
Whether you are starting to organize your finances or looking for ways to improve existing habits, taking small and consistent steps can create meaningful progress.
Financial confidence is not simply about earning more money.
It is about knowing where your money goes, preparing for the future, and developing habits that help you feel more comfortable with your financial decisions.
The first step toward greater financial confidence is understanding your current financial situation. Reviewing your income, regular expenses, savings, debts, and other financial responsibilities can give you a clearer picture of your overall position. This process may seem simple, but having accurate information can make financial decisions easier. When you understand your starting point, you can identify areas that need attention and recognize opportunities to improve without creating unnecessary pressure.
Creating a practical spending plan can help bring more structure to your finances. A spending plan allows you to decide how your income will be used for essential expenses, personal priorities, savings, and future goals. Rather than thinking of a budget as a limitation, consider it a way to give your money direction. A flexible approach can make it easier to handle changing expenses while still maintaining progress toward important financial objectives.
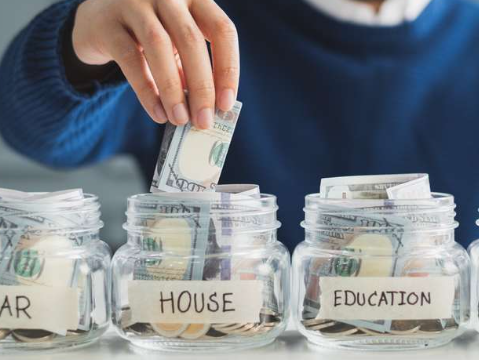
Developing a regular savings habit is another valuable step toward financial confidence. Saving does not always require large amounts of money. Setting aside a manageable portion of your income consistently can gradually create a stronger financial cushion. As your circumstances change, you can review your savings amount and make adjustments when appropriate. The important part is creating a habit that fits comfortably within your overall financial plan.
An emergency savings fund can provide additional peace of mind when unexpected expenses appear. Everyday life can bring situations such as home repairs, vehicle expenses, temporary changes in income, or other unplanned costs. Having money reserved for these circumstances can reduce the need to rely on credit or disrupt other financial goals. Building an emergency fund can take time, so focus on making steady progress rather than trying to reach a large target immediately.
Managing debt carefully is also an important part of developing financial confidence. Understanding how much you owe, when payments are due, and how interest affects your balances can help you make better decisions. Paying required bills on time and creating a realistic repayment strategy can gradually improve your financial position. If you have several financial obligations, organizing them clearly can make the repayment process feel more manageable and easier to track.
Setting specific financial goals gives your money a clear purpose. Your goals might include building savings, paying down debt, preparing for a major purchase, supporting your family, developing your career, or preparing for retirement. Clear goals make it easier to measure progress because you have something specific to work toward. Breaking larger objectives into smaller milestones can also make long-term goals feel more realistic and achievable.
Learning about personal finance can strengthen your confidence over time. You do not need to become an expert in every area of finance. Instead, focus on understanding topics that are relevant to your current situation. Learning about budgeting, saving, credit, investing, taxes, insurance, and retirement planning can help you make more informed choices. Using trustworthy educational resources can also help you avoid making decisions based solely on advertisements, social media trends, or unverified claims.
Thoughtful spending habits can make a meaningful difference in everyday financial life. Before making a purchase, consider whether it fits your current priorities and financial plan. This does not mean that you should avoid spending money on things you enjoy. Instead, mindful spending encourages you to make choices that provide value while keeping your larger goals in view. Over time, becoming more intentional with spending can create additional room for savings and other priorities.
Planning for long-term needs is another important part of financial confidence. Retirement may seem distant, but preparing gradually can make the process easier. Depending on your circumstances, contributing regularly to appropriate retirement accounts or long-term savings plans may help you prepare for the future. Reviewing your retirement strategy periodically allows you to consider changes in income, goals, and personal circumstances while keeping your plans aligned with your expectations.
Protecting your financial information should also be part of your overall approach. Online banking and digital financial services make money management convenient, but they also require responsible security habits. Using strong and unique passwords, enabling available account security features, reviewing account activity, and being cautious with unfamiliar messages or requests can help reduce common risks. Taking a few minutes to review your financial accounts regularly can also help you notice unusual activity sooner.
Improving your earning potential can provide another path toward greater financial flexibility. Developing professional skills, pursuing additional education, improving qualifications, or exploring suitable career opportunities may create opportunities for increased income. When additional income becomes available, consider how it can support your priorities rather than automatically increasing everyday spending. Directing some additional income toward savings, debt reduction, or long-term goals can strengthen your financial position.
Financial confidence can also benefit from open communication within families and households. When people share financial responsibilities, discussing spending priorities, savings goals, and future plans can help everyone understand the bigger picture. Clear conversations can reduce misunderstandings and encourage cooperation. Financial discussions do not need to be complicated. Regular and respectful communication can make it easier to work together toward shared objectives.
Building confidence with money requires patience and consistency. Financial progress rarely happens because of one major decision. More often, it develops through everyday choices repeated over time. Tracking expenses, saving regularly, paying bills responsibly, reviewing goals, and learning new information can gradually create stronger financial habits. Recognizing small achievements can also help maintain motivation and make the process feel rewarding.
Reviewing your financial plan regularly is another useful habit. Your income, expenses, responsibilities, and priorities may change as life develops. A plan that worked well several years ago may no longer fit your current circumstances. Taking time to review your financial situation allows you to adjust your spending, savings, and goals when necessary. Flexibility is important because a financial plan should support your life rather than become an unnecessary source of stress.
Technology can make financial organization easier for many people. Budgeting applications, banking tools, savings trackers, and financial calculators can help you monitor information and organize routine tasks. The best tools are those that are easy for you to understand and use consistently. Technology should support your financial habits rather than replace thoughtful decision-making.
It is also important to avoid comparing your financial progress with someone else’s. People have different incomes, responsibilities, opportunities, and personal circumstances. Comparing your situation with another person’s can create unnecessary pressure and may encourage decisions that do not fit your needs. Instead, focus on your own progress and consider whether your current choices are moving you closer to your goals.
For more complicated financial situations, professional guidance may be useful. A qualified financial professional can help you understand options and develop strategies that are appropriate for your individual circumstances. When considering professional assistance, look for reputable qualifications, transparent fees, clear communication, and advice that reflects your goals and risk tolerance. Taking time to understand the services being offered can help you make a more informed choice.
Achieving financial confidence step by step is ultimately about creating clarity, developing consistent habits, and making decisions that support your priorities. You do not need to change everything at once. Start by understanding your financial position, create a realistic spending plan, build savings, manage debt responsibly, set meaningful goals, and continue learning as your circumstances evolve. Each thoughtful decision can contribute to greater stability and peace of mind.
Financial confidence grows through experience. As you become more familiar with your income, expenses, savings, goals, and financial choices, money can begin to feel less uncertain and more manageable. By focusing on steady progress rather than perfection, you can create a practical financial approach that supports both your present needs and your future aspirations. Step by step, consistent financial habits can help you feel more prepared, informed, and confident about the path ahead.