Personal finance is an essential life skill that helps people make informed decisions about earning, saving, spending, and planning for the future.
While financial topics may seem complicated at first, the basic principles are straightforward and can benefit anyone, regardless of income level.
Learning how to manage money wisely creates a stronger foundation for reaching personal goals, handling unexpected expenses, and building long-term financial confidence.
The journey toward better financial management begins with understanding where your money comes from and where it goes. Taking time to review your income and expenses provides valuable insight into spending habits. Many people are surprised to discover how small daily purchases can add up over time. Tracking expenses for a month often reveals opportunities to reduce unnecessary costs without sacrificing quality of life.
Creating a practical budget is one of the most effective ways to organize personal finances. A budget is simply a plan for how money will be used each month. Instead of viewing a budget as a restriction, it can be seen as a helpful guide that allows people to prioritize what matters most. A successful budget includes essential expenses such as housing, food, transportation, utilities, savings, and discretionary spending. The goal is to ensure that spending aligns with personal priorities while avoiding unnecessary financial stress.
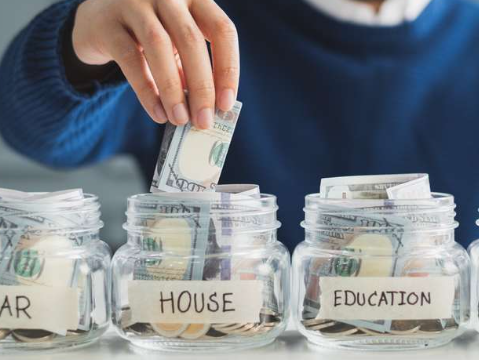
Saving money plays an equally important role in financial stability. Even small, consistent contributions to savings can grow over time. Setting aside a portion of each paycheck before spending on other items encourages a habit of saving first. Many financial experts recommend establishing an emergency fund that can help cover unexpected costs such as medical bills, vehicle repairs, or temporary income interruptions. Having savings available provides peace of mind and reduces the need to rely on borrowing during emergencies.
Setting financial goals gives purpose to everyday money decisions. Goals may include purchasing a home, paying for education, traveling, starting a business, or preparing for retirement. Clear goals help individuals stay motivated because each saving or budgeting decision supports a larger objective. Dividing larger goals into smaller milestones makes progress easier to measure and encourages consistent effort over time.
Managing debt responsibly is another important aspect of personal finance. Borrowing can be useful when handled carefully, but it is beneficial to understand the terms and repayment requirements before taking on new financial obligations. Making payments on time, avoiding unnecessary borrowing, and keeping balances manageable contribute to healthier financial habits. Responsible debt management also supports a positive credit history, which may be helpful when applying for future loans or housing.
Understanding credit is valuable because it affects many aspects of personal finance. Credit represents a person’s history of borrowing and repaying money. Lenders often review credit information when evaluating loan applications. Paying bills on time, keeping borrowing within manageable limits, and reviewing credit reports periodically are practical ways to maintain a healthy financial profile. Building good credit typically takes time, but consistent financial responsibility can lead to positive results.
Investing introduces another opportunity for long-term financial growth. Investments allow money to potentially grow through various financial assets such as stocks, bonds, mutual funds, or exchange-traded funds. Every investment carries some level of risk, and returns are never guaranteed. Learning about different investment options, understanding personal financial goals, and considering time horizons before investing can help individuals make informed decisions that match their comfort level and objectives.
Retirement planning is an important part of personal finance regardless of age. Starting early allows savings to benefit from long-term growth, although it is never too late to begin planning. Regular contributions to retirement accounts, combined with consistent investing over many years, may help individuals prepare for future financial needs. Reviewing retirement plans periodically ensures they continue to align with changing life circumstances and goals.
Insurance also contributes to a well-rounded financial plan. Health, home, renters, auto, and life insurance each serve different purposes in protecting against unexpected financial challenges. Choosing appropriate coverage depends on individual circumstances, family responsibilities, and financial priorities. Reviewing policies occasionally helps ensure that coverage remains suitable as life changes over time.
Financial education is an ongoing process rather than a one-time achievement. Economic conditions, financial products, and personal circumstances evolve over time. Reading trusted financial resources, attending educational workshops, and seeking information from reliable sources can improve financial knowledge. The more informed people become, the more confident they often feel when making important financial decisions.
Technology has made personal finance management more convenient than ever. Budgeting apps, online banking, automatic bill payments, and digital savings tools allow individuals to monitor finances efficiently. Many financial institutions provide spending summaries, savings goals, and budgeting features that simplify money management. Using these tools wisely can save time while improving financial awareness.
Developing healthy spending habits supports long-term financial success. Comparing prices before making purchases, distinguishing between needs and wants, and avoiding impulse buying can improve financial stability. Planning major purchases in advance often leads to better decisions and reduces unnecessary financial pressure. Small improvements in daily spending habits frequently produce meaningful long-term results.
Financial planning is not only about numbers but also about personal values. Every individual has unique priorities, lifestyles, and aspirations. A financial plan should reflect those personal goals rather than comparing progress with others. Consistency and patience are often more valuable than trying to achieve rapid financial results.
Families can also benefit from discussing finances openly. Age-appropriate conversations about budgeting, saving, and responsible spending help children and young adults develop positive financial habits early in life. Financial literacy becomes a valuable skill that supports independence and informed decision-making throughout adulthood.
Reviewing finances regularly allows individuals to adapt to changes in income, expenses, and personal goals. Life events such as career changes, marriage, home ownership, or expanding families may require adjustments to financial plans. Periodic reviews help ensure that budgets, savings strategies, and investment plans continue to support current priorities.
One common mistake is expecting perfection from the beginning. Financial improvement usually happens through steady progress rather than dramatic changes. Unexpected expenses and temporary setbacks are normal parts of life. Adjusting plans when circumstances change and continuing to move forward can lead to lasting financial resilience.
Building multiple sources of income may also strengthen financial security for some individuals. This could include freelance work, part-time employment, developing new skills, or other legitimate income opportunities that fit personal schedules and interests. Diversifying income sources may provide additional flexibility while supporting long-term financial goals.
Patience remains one of the most valuable qualities in personal finance. Building savings, reducing debt, and growing investments often require consistent effort over many years. Focusing on long-term progress rather than short-term fluctuations encourages better decision-making and helps individuals remain committed to their financial plans.
The complete guide to personal finance is ultimately built on simple, practical habits practiced consistently over time. Budgeting thoughtfully, saving regularly, managing debt responsibly, learning continuously, and planning for the future all contribute to greater financial confidence. Every positive financial decision, no matter how small, becomes part of a stronger financial foundation that supports future opportunities and lasting peace of mind.