Personal finance is a skill that anyone can learn.
While money management may seem complicated at first, taking a practical approach can make financial decisions easier and more rewarding.
Instead of searching for quick fixes or unrealistic shortcuts, focusing on consistent habits helps create a stronger financial future over time.
Personal finance is not about earning the highest income or living with strict limitations. It is about making thoughtful choices that support your goals, reduce unnecessary stress, and provide greater financial flexibility. Whether you are just beginning your financial journey or looking to improve your current habits, practical strategies can make a meaningful difference.
One of the first steps toward financial success is understanding your income and expenses. Knowing how much money comes in each month and where it goes creates a clear picture of your financial situation. Many people are surprised to discover small recurring expenses that gradually add up. Reviewing spending regularly allows you to identify opportunities to save without giving up the things that matter most.
Creating a realistic budget is another valuable habit. A budget should reflect your lifestyle and priorities instead of feeling restrictive. When you assign a purpose to your income, it becomes easier to manage everyday expenses while setting aside money for future goals. A flexible budget also allows room for unexpected costs, making it easier to adjust when life changes.
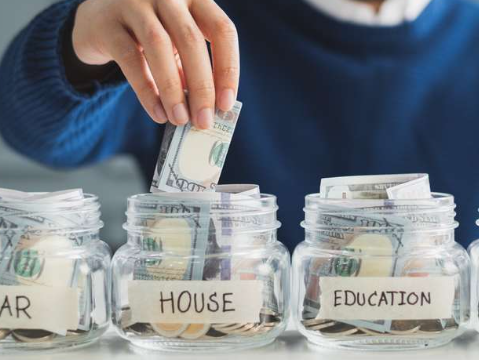
Saving money consistently is an important part of practical personal finance. Even small contributions can grow over time through consistency. Setting aside a portion of each paycheck before spending on nonessential purchases helps build positive financial habits. Automated savings transfers can make this process even easier by reducing the temptation to spend money intended for future needs.
An emergency fund provides financial security during unexpected situations. Car repairs, medical expenses, home maintenance, or temporary income changes can happen without warning. Having savings available for these events reduces financial pressure and helps avoid relying on high-interest borrowing. Building an emergency fund takes time, but every contribution strengthens your financial foundation.
Managing debt responsibly is another essential aspect of personal finance. Not all debt is the same, but understanding repayment terms and making timely payments helps maintain financial stability. Paying more than the minimum payment whenever possible may reduce interest costs over time. Staying organized with payment schedules also helps protect your credit history.
Credit plays an important role in many financial decisions. Responsible credit use demonstrates reliability and may support future opportunities such as renting a home, qualifying for loans, or obtaining favorable financing terms. Paying bills on time and keeping balances manageable are practical habits that contribute to a healthy credit profile.
Setting financial goals gives purpose to everyday money decisions. Some goals may be short-term, such as saving for a vacation or purchasing new equipment. Others may focus on longer-term objectives, including homeownership, retirement savings, or funding education. Breaking larger goals into smaller milestones makes progress easier to track and keeps motivation strong.
Practical investing is another way to support long-term financial growth. Investing involves both opportunities and risks, so learning the basics before making decisions is valuable. Diversification, patience, and maintaining a long-term perspective are commonly discussed principles that many investors consider. Educational resources can help individuals better understand different investment options before deciding which may fit their circumstances.
Financial education is an ongoing process. Economic conditions, financial products, and personal goals naturally evolve over time. Reading trusted financial resources, attending educational workshops, or following reliable experts can help improve financial knowledge. The more informed you become, the more confident you may feel when making important financial decisions.
Technology has also made personal finance more accessible. Budgeting apps, online banking, expense trackers, and savings calculators allow people to monitor their finances with greater convenience. These tools can simplify record keeping and provide helpful insights into spending patterns, making it easier to stay on track with financial goals.
Lifestyle choices have a significant influence on financial well-being. Comparing purchases carefully, planning major expenses in advance, and avoiding impulsive buying decisions can improve overall financial health. This does not mean avoiding enjoyment but rather making intentional choices that align with personal priorities.
Building multiple income sources may also contribute to greater financial flexibility. Some individuals explore freelance work, consulting, online businesses, or investment income alongside their primary employment. Additional income can support savings goals, accelerate debt repayment, or provide extra financial security. Before pursuing any opportunity, it is wise to evaluate the time commitment, potential risks, and suitability for your personal situation.
Insurance is another practical component of financial planning. Appropriate coverage for health, property, vehicles, or life circumstances can help reduce the financial impact of unexpected events. Reviewing insurance needs periodically ensures that coverage continues to match changing situations while avoiding unnecessary expenses.
Retirement planning benefits from starting early whenever possible. Even modest contributions made consistently over many years may have the opportunity to grow through long-term investing. Individuals often review retirement accounts regularly and adjust contributions as income changes. Beginning with manageable amounts can make long-term saving feel more achievable.
Communication also plays an important role in household finances. Families and partners who openly discuss budgets, savings goals, and financial priorities often find it easier to make shared decisions. Honest conversations help reduce misunderstandings and encourage teamwork when managing money together.
Financial success should not be measured only by wealth. Feeling prepared for unexpected expenses, making informed decisions, and having the ability to work toward meaningful goals are equally valuable achievements. Personal finance is ultimately about creating stability and supporting the life you want to build.
Patience is one of the most valuable qualities in personal finance. Meaningful progress usually develops through consistent habits rather than dramatic changes. Small improvements repeated month after month often lead to significant long-term results. Celebrating milestones along the way can provide motivation to continue building healthy financial habits.
Everyone’s financial journey is unique. Income levels, personal responsibilities, family situations, and future aspirations vary widely. Practical personal finance focuses on making thoughtful decisions based on individual circumstances instead of comparing yourself to others. Flexibility and regular financial reviews allow plans to adapt as life changes.
Personal Finance Made Practical is ultimately about turning simple financial principles into everyday habits. Budgeting thoughtfully, saving consistently, managing debt responsibly, learning continuously, and planning for the future all contribute to stronger financial confidence. By focusing on steady progress rather than perfection, anyone can develop a healthier relationship with money and build a more secure financial future over time.