Financial confidence is not about having a huge income or becoming an expert in investing overnight.
It is about feeling comfortable with the financial decisions you make each day and knowing that your choices support your goals.
Many people believe that money management is complicated, but the truth is that a few simple habits can make a meaningful difference over time.
Building financial confidence starts with understanding where your money goes and creating routines that help you feel more in control.
The journey toward greater financial confidence begins with awareness. Taking time to review your income, expenses, and savings gives you a clear picture of your current financial situation. This step is not about judging past decisions but about understanding your starting point. Once you know where you stand, it becomes much easier to make thoughtful choices that match your priorities.
One of the simplest ways to strengthen your financial confidence is by creating a realistic budget. A budget is not designed to limit your freedom. Instead, it serves as a guide that helps you use your money with purpose. When you know how much you earn and how much you spend on essentials, entertainment, savings, and other priorities, you can make decisions with greater peace of mind. A flexible budget that reflects your lifestyle is often easier to maintain than one with overly strict rules.
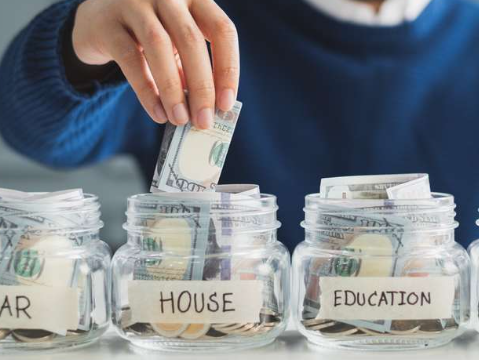
Saving money consistently is another important habit that supports financial confidence. Many people think they need to save large amounts to make progress, but even small contributions can become meaningful over time. Setting aside a portion of your income each month creates a sense of security and prepares you for unexpected expenses. Regular saving also builds positive financial habits that become easier to maintain as time goes on.
An emergency fund can provide additional confidence during uncertain times. Life often brings unexpected events, such as vehicle repairs, medical expenses, or temporary changes in income. Having money set aside for emergencies can reduce financial stress and help you manage these situations more comfortably. Building an emergency fund may take time, but consistent contributions can gradually create a valuable financial cushion.
Understanding the difference between needs and wants can also improve financial decision-making. Essential expenses such as housing, food, transportation, and healthcare generally take priority over optional purchases. This does not mean you should never enjoy entertainment or personal treats. Instead, making intentional spending decisions allows you to enjoy the things you value while still working toward your long-term financial goals.
Setting realistic financial goals gives your money a clear purpose. Some people focus on saving for a vacation, purchasing a home, continuing their education, or preparing for retirement. Others may simply want to reduce financial stress and improve their monthly cash flow. Whatever your goals may be, writing them down and reviewing your progress regularly can help keep you motivated. Clear goals also make it easier to decide how to allocate your resources.
Learning about personal finance is an investment in yourself. You do not need an advanced degree to understand the basics of budgeting, saving, responsible borrowing, and long-term planning. Reliable books, educational websites, community programs, and financial education resources can provide valuable information. Taking time to learn at your own pace builds confidence and helps you make informed financial choices.
Responsible use of credit can also support financial confidence. Credit can be a useful financial tool when managed carefully. Paying bills on time, borrowing only what you can comfortably repay, and understanding loan terms before making commitments can contribute to healthier financial habits. Developing these practices helps reduce financial pressure and supports long-term financial stability.
Tracking your spending does not need to be difficult. Many people find success by reviewing their expenses once a week or once a month. This simple habit helps identify spending patterns and areas where small adjustments may create additional savings. Even minor changes, such as preparing meals at home more often or reviewing subscription services, can have a positive impact over time.
Building financial confidence also means preparing for the future. Long-term planning may include retirement savings, education funds, or other personal goals. Starting early can provide more opportunities for your savings to grow over time. Even if you begin with modest contributions, consistency often matters more than perfection. Every positive financial step adds to your overall progress.
It is also helpful to recognize that financial journeys are unique. Comparing your situation to someone else’s may create unnecessary pressure. Everyone has different incomes, responsibilities, goals, and life experiences. Focusing on your own progress allows you to celebrate improvements and make decisions that reflect your personal circumstances rather than outside expectations.
Communication plays an important role in financial confidence, especially for families and couples. Open conversations about spending, saving, and financial priorities can help reduce misunderstandings and support shared goals. Working together to create a financial plan often strengthens both financial stability and personal relationships.
Technology has made money management more accessible than ever. Budgeting apps, online banking tools, automatic savings features, and spending alerts can simplify financial organization. While technology is helpful, the most important factor remains consistent financial habits. Simple routines practiced regularly often have a greater impact than complicated financial strategies.
Financial confidence also grows when you celebrate small achievements. Reaching a savings milestone, paying off a balance, following your budget for several months, or building an emergency fund are all meaningful accomplishments. Recognizing these successes helps maintain motivation and reminds you that progress happens one step at a time.
Unexpected financial challenges may still occur despite careful planning. During these moments, flexibility becomes an important skill. Reviewing your budget, adjusting priorities, and seeking reliable financial information can help you respond thoughtfully rather than reacting emotionally. Every challenge also provides an opportunity to learn and strengthen your financial habits.
Patience is another valuable part of financial success. Significant financial improvements rarely happen overnight. Building savings, reducing debt, and reaching long-term goals often require steady effort over many months or years. Staying consistent with positive habits allows gradual progress to become lasting success.
Confidence with money is closely connected to healthy decision-making. Rather than chasing quick financial solutions or making impulsive choices, thoughtful planning often leads to more sustainable outcomes. Taking time to evaluate options before making major financial decisions can help you feel more secure and prepared.
As financial confidence grows, many people experience benefits beyond their bank accounts. Feeling more organized, reducing financial uncertainty, and having greater clarity about personal goals can contribute to overall well-being. Financial confidence is not measured by how much money you have but by how effectively you manage the resources available to you.
Financial confidence made simple is ultimately about building practical habits that support your everyday life. By understanding your finances, creating a realistic budget, saving consistently, setting achievable goals, continuing to learn, and making thoughtful spending decisions, you can develop greater confidence with your money over time. Every positive choice, no matter how small, contributes to a stronger financial foundation. With patience, consistency, and a focus on steady improvement, financial confidence becomes an achievable goal that supports both present needs and future opportunities.