Building a strong financial foundation is one of the most practical steps you can take toward a more confident and organized future.
Good financial habits are not only for people with high incomes or extensive savings.
Anyone can begin improving their financial position by understanding where their money goes, making thoughtful decisions, and creating routines that support long-term goals.
A healthy financial foundation does not happen overnight. It develops gradually through consistent choices. By focusing on the basics, you can create a financial system that helps you handle everyday expenses, prepare for unexpected situations, and work toward goals that matter to you.
Understand Your Current Financial Picture
The first step toward stronger finances is understanding your current situation. Before making major changes, take some time to look at your income, regular expenses, savings, and financial obligations.
Review your monthly income and compare it with what you normally spend. Include everyday costs such as housing, food, transportation, utilities, subscriptions, and personal expenses. It can also be helpful to review less frequent expenses, such as annual fees, maintenance, gifts, or travel.
This simple review can reveal patterns that may otherwise be easy to overlook. You might discover that certain expenses are larger than expected or that small recurring purchases add up over time. Understanding these patterns gives you useful information for making better decisions.
Create a Realistic Spending Plan
Once you understand your finances, create a spending plan that reflects your actual lifestyle. A good plan should be practical rather than restrictive.
Start with essential expenses and financial commitments. Then consider savings, personal spending, and other priorities. The goal is to give every part of your income a purpose while leaving enough flexibility for normal changes in your month.
Instead of trying to eliminate every enjoyable expense, look for balance. A spending plan that is too difficult to maintain can become frustrating. A realistic approach makes it easier to stay consistent and adjust when circumstances change.
Review your plan regularly. Income and expenses can change over time, so your financial strategy should be flexible enough to adapt.
Build an Emergency Fund
An emergency fund can provide an important layer of financial stability. Unexpected expenses can happen at almost any time, from a vehicle repair to a temporary reduction in income or an urgent household expense.
Rather than trying to build a large reserve immediately, start with an amount that feels achievable. Setting aside a small amount regularly can create meaningful progress over time.
Keep emergency savings in an accessible account that is separate from everyday spending money. This can make it easier to distinguish between funds intended for unexpected needs and money available for routine purchases.
As your financial situation improves, you can gradually increase your emergency reserve. The appropriate amount depends on your income, household situation, essential expenses, and level of financial flexibility.
Manage Debt Thoughtfully
Debt can be a normal part of personal finance, but managing it carefully is important. Begin by understanding what you owe, the interest rates involved, and the required payments.
Make required payments on time and consider directing additional money toward higher-cost debt when appropriate. At the same time, avoid taking on new obligations simply because a payment appears affordable. Looking at the total cost of borrowing can provide a clearer picture than focusing only on monthly payments.
If managing several debts feels complicated, organizing them into a simple overview can make the situation easier to understand. The key is to approach debt with a clear plan rather than allowing it to become an overlooked part of your finances.
Make Saving a Regular Habit
Saving becomes easier when it is treated as a regular financial activity rather than something you do only when money is left over.
Consider setting a specific amount or percentage of your income aside regularly. Even modest contributions can become valuable over time because consistency matters.
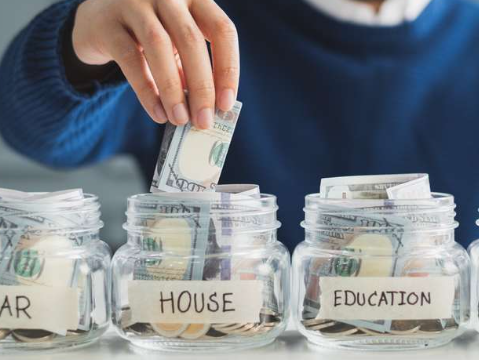
You may also find it useful to separate savings according to different purposes. For example, one account or category could be dedicated to short-term goals, while another could support longer-term plans.
Automatic transfers can make saving more convenient. Moving money shortly after receiving income can help turn saving into a routine and reduce the temptation to spend those funds elsewhere.
Protect Your Financial Progress
A strong financial foundation also involves protecting what you have built. Keeping important financial documents organized and reviewing accounts periodically can help you stay aware of your situation.
Insurance can also play a role in managing certain financial risks. Depending on your circumstances, appropriate coverage may help reduce the financial impact of unexpected events.
It is also wise to be cautious with financial information. Use strong passwords, enable available security features, and review account activity regularly. Protecting your accounts is an important part of maintaining financial stability.
Set Meaningful Financial Goals
Financial goals give your money a clear direction. Your goals might include saving for education, preparing for a major purchase, planning for retirement, or simply creating more financial flexibility.
Try to make your goals specific and realistic. Instead of saying that you want to save more, decide what you are saving for and establish a target amount and general timeframe.
Breaking a larger goal into smaller milestones can make progress easier to track. Each milestone can provide a sense of accomplishment while keeping your attention on the larger objective.
Your priorities may change as your life develops, so review your goals from time to time and make adjustments when necessary.
Learn the Basics of Investing
Once your everyday finances are organized and you have established appropriate savings, you may want to learn more about investing. Investing can support long-term financial goals, but it involves uncertainty and the possibility of losing money.
Before investing, learn about concepts such as diversification, risk, fees, time horizon, and different types of investments. Avoid making decisions based solely on short-term trends or promises of easy returns.
Your investment choices should reflect your personal circumstances, goals, and tolerance for risk. Taking time to understand what you are considering can help you make more informed decisions.
For complicated financial decisions, professional guidance from a qualified financial adviser may also be worth considering.
Review Your Financial Habits
Building financial strength is an ongoing process. A plan that works well today may need to change as your income, expenses, responsibilities, and goals evolve.
Set aside time periodically to review your spending, savings, debt, and progress toward your goals. Look for areas that are improving and areas that may need attention.
Do not expect perfection. A missed savings contribution or an unexpected expense does not mean your financial plan has failed. The more important habit is returning to your plan and continuing forward.
Build Confidence Through Consistency
A strong financial foundation is ultimately built through small decisions repeated over time. Understanding your finances, creating a realistic spending plan, maintaining emergency savings, managing debt responsibly, saving regularly, and setting meaningful goals can all contribute to greater financial stability.
You do not need to change everything at once. Start with one manageable improvement and build from there. As good habits become part of your routine, managing money can become less stressful and more intentional.
Financial progress is not about comparing your situation with someone else’s. It is about creating a system that supports your own needs and priorities. With patience, awareness, and consistent effort, you can build a financial foundation that gives you greater flexibility today and a stronger starting point for the future.