Managing money does not have to feel complicated.
Whether you are trying to spend more thoughtfully, build savings, reduce financial stress, or simply understand where your money goes, small improvements can make a meaningful difference over time.
Better finances are rarely about making perfect decisions.
They are about developing practical habits that support your everyday needs and your longer-term goals.
A useful place to begin is with a clear picture of your current financial situation. Many people know roughly how much they earn each month but are less certain about how much they actually spend. Reviewing your income and regular expenses can help you understand your financial patterns without judgment. Look at essential costs such as housing, food, transportation, utilities, and other recurring commitments. Then consider flexible spending, including entertainment, dining out, shopping, and subscriptions. This simple review can show you where your money is going and where adjustments may be possible.
Once you understand your spending, consider creating a realistic monthly plan. A budget should be a helpful guide rather than a strict set of rules that makes everyday life uncomfortable. Start by making sure essential expenses are covered. Then decide how much you would like to set aside for savings and how much is available for flexible spending. If your income or expenses change from month to month, allow some room for those differences instead of relying on an overly precise target.
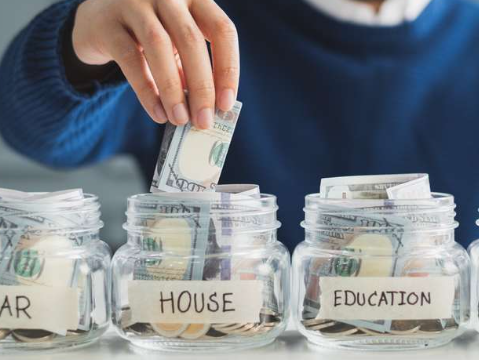
Saving can become easier when it has a specific purpose. Instead of thinking only about saving a large amount, consider separate goals that feel achievable. You might be saving for an unexpected expense, a future purchase, education, travel, or another personal priority. Even modest contributions can help create a stronger financial cushion when they are made consistently. If possible, setting up an automatic transfer after receiving income can make saving a regular part of your routine.
An emergency fund can also provide useful financial flexibility. Unexpected car repairs, household costs, temporary income changes, or other surprises can put pressure on a budget. Having money reserved for genuine emergencies may reduce the need to rely on new borrowing when an unexpected expense occurs. The appropriate amount depends on your circumstances, income stability, essential expenses, and personal responsibilities, so focus on building a reserve that makes sense for your situation.
Managing debt is another important part of financial well-being. If you have several debts, make sure you understand the balance, interest rate, minimum payment, and due date for each one. Paying bills on time can help you avoid unnecessary late charges and keep your financial routine organized. When considering how to repay debt faster, you can compare approaches based on interest costs, payment amounts, and the strategy that you are most likely to maintain. If your situation feels difficult to manage, a qualified financial counselor or other trusted professional may be able to provide guidance based on your circumstances.
It is also worth paying attention to recurring expenses. A subscription or service may seem inexpensive on its own, but several small recurring charges can become a significant part of a monthly budget. Reviewing these expenses occasionally can help you identify services you no longer use or costs that may have changed. Before canceling an important service or financial product, however, consider whether doing so could create another cost or affect something you rely on.
Financial progress is not only about cutting spending. Increasing your financial knowledge can be just as valuable. Take time to learn basic concepts such as interest, inflation, credit, savings, taxes, insurance, and investment risk. Reliable information can help you ask better questions and make decisions with greater confidence. When researching financial products or services, compare the terms carefully and pay attention to fees, conditions, risks, and eligibility requirements rather than relying only on promotional language.
It is equally important to be cautious with financial promises that sound too good to be true. Be skeptical of claims that suggest guaranteed profits, effortless wealth, or unusually high returns with little or no risk. Financial decisions should be based on information you can verify and understand. If an opportunity creates pressure to act immediately or asks for sensitive information without a clear reason, take a step back and investigate before making a commitment.
Your financial priorities may also change throughout life. A plan that works when you are starting your career may need to change when your household responsibilities, income, or goals change. Review your budget and financial goals periodically instead of expecting one plan to work forever. A short review every few months can help you identify changes and make adjustments before small issues become larger ones.
Technology can make financial organization more convenient, but it should be used thoughtfully. Banking applications, spreadsheets, budgeting tools, and calendar reminders can help you monitor transactions and remember important dates. At the same time, protect your accounts by using strong, unique passwords, keeping software updated, and being careful about unexpected messages requesting financial information. Convenience should never come at the expense of basic security.
Perhaps the most important lesson is that better finances are built gradually. You do not need to transform your entire financial life in one weekend. Start with one useful habit, such as reviewing your spending, creating a savings routine, organizing bills, or learning more about a financial topic you do not yet understand. Once that habit becomes comfortable, you can build on it.
Money management is ultimately personal. There is no single budget, savings target, or financial strategy that is appropriate for everyone. Your income, responsibilities, goals, and comfort with financial risk all matter. The goal is not to compare your progress with someone else’s. It is to create a financial routine that is clear, sustainable, and suited to your circumstances.
Better finances are less about perfection and more about awareness, preparation, and consistency. By understanding your money, planning around your priorities, preparing for unexpected expenses, and making informed choices, you can create a stronger foundation for the future. Take one manageable step today, review your progress regularly, and allow your financial habits to improve over time. For personal financial decisions, consider seeking advice from a qualified professional who can take your individual circumstances into account.