Financial success is a goal that can mean something different to everyone.
For one person, it may mean paying bills comfortably and maintaining an emergency fund.
For another, it may involve purchasing a home, preparing for retirement, supporting a family, or creating greater flexibility in everyday life.
Regardless of the specific goal, financial success generally begins with understanding how money works and developing habits that support long-term stability.
A healthy financial life does not require earning an extremely high income. In many cases, progress comes from making thoughtful choices consistently. Understanding your income, expenses, savings, debt, and future goals can help you make decisions with greater confidence. The most useful financial strategies are often practical, realistic, and easy to maintain over time.
Understanding Your Current Financial Position
Before working toward financial goals, it is helpful to understand where you currently stand. Start by looking at your regular income and comparing it with your typical expenses. This simple comparison can reveal whether your finances have enough room for saving, unexpected costs, and future plans.
Knowing your spending patterns is also important. Everyday purchases can add up over time, especially when they are made without much planning. Reviewing several weeks or months of expenses can help you identify areas where your money is going and determine whether those choices match your priorities.
This process should not be about judging yourself. Financial awareness is simply a way to gain a clearer picture of your situation. Once you understand your starting point, it becomes easier to make reasonable improvements.
Creating a Practical Spending Plan
A spending plan can provide structure without making everyday life feel restrictive. Instead of focusing only on cutting expenses, consider how you want your income to support your priorities.
Essential costs such as housing, food, transportation, utilities, and insurance usually come first. After these needs are covered, you can consider savings, debt payments, personal goals, and discretionary spending.
A flexible plan is often easier to maintain than an overly strict one. Unexpected expenses and changing circumstances are part of life, so your financial plan should have enough room to adapt. The goal is not perfection. The goal is to create a system that helps you make intentional decisions.
Building an Emergency Fund
Unexpected expenses can create financial stress when there is no money available to handle them. An emergency fund can provide a useful layer of protection for situations such as urgent repairs, temporary income changes, or other necessary expenses.
The amount you need depends on your circumstances, including your income, household responsibilities, and regular expenses. Rather than worrying about reaching a specific number immediately, focus on building the habit of saving consistently.
Even modest contributions can become meaningful over time. Keeping emergency savings separate from everyday spending may also make it easier to preserve the money for genuine financial needs.
Managing Debt Responsibly
Debt can be a useful financial tool in certain circumstances, but it should be managed carefully. Understanding interest rates, payment schedules, and total repayment costs can help you make informed choices.
When paying down debt, consistency matters. Making required payments on time can help you avoid unnecessary fees and additional financial pressure. If you have multiple debts, reviewing their interest rates and balances can help you determine a repayment approach that fits your circumstances.
It is also worth considering how new borrowing could affect your future budget. Before taking on additional debt, think about whether the payment will remain manageable if your income or expenses change.
Developing a Savings Habit
Saving becomes easier when it is treated as a regular financial activity rather than something that happens only when extra money is available. Setting aside a portion of income when possible can help create steady progress.
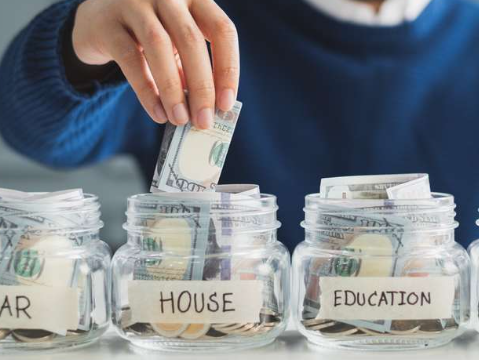
Automatic transfers may make saving more convenient because the money can be moved into a savings account without requiring a decision every time. You can also create separate savings goals for different purposes, such as education, travel, a home purchase, or future expenses.
The important point is to make the habit realistic. A sustainable savings routine is generally more useful than setting an ambitious target that becomes difficult to maintain.
Learning About Investing
Investing can play a role in long-term financial planning, particularly when the goal is to build wealth over many years. However, investing involves risk, and different investments can behave differently depending on market conditions.
Before investing, it is useful to understand basic concepts such as diversification, time horizon, fees, risk tolerance, and the relationship between potential returns and potential losses. Avoid making financial decisions based solely on trends, social media discussions, or promises of quick profits.
A long-term perspective can help investors focus on their broader goals rather than reacting emotionally to short-term market movements. Learning gradually and using reliable information can support more informed decisions.
Planning for Long-Term Goals
Financial success becomes easier to pursue when goals are clearly defined. A goal might involve building a certain level of savings, preparing for retirement, reducing debt, starting a business, or improving financial security for your household.
Consider how much time you have to reach each goal and what resources may be required. Breaking a large objective into smaller milestones can make it feel more manageable.
Long-term planning should also be reviewed periodically. Your income, family circumstances, expenses, and priorities may change, so your financial strategy may need to change as well.
Improving Financial Knowledge
Financial education is one of the most valuable tools available to anyone who wants to improve their money habits. Learning about budgeting, taxes, insurance, credit, saving, investing, and retirement planning can make everyday financial decisions easier to understand.
You do not need to become an expert in every area. Start with subjects that directly affect your current situation. As your knowledge grows, you may feel more comfortable asking questions, comparing options, and evaluating financial information.
Reliable sources are particularly important because financial information found online can vary widely in quality. Be cautious of claims that promise guaranteed results, unusually high returns, or effortless wealth.
Maintaining Healthy Financial Habits
Financial success is usually the result of repeated actions rather than one major decision. Reviewing your finances regularly, spending thoughtfully, saving consistently, and learning from previous choices can gradually improve your financial position.
It is also important to allow room for enjoyment. A healthy financial plan should support your quality of life rather than make every purchase feel stressful. Finding a balance between present needs and future goals can make financial habits more sustainable.
Final Thoughts
Financial success is not a single destination. It is an ongoing process of making informed choices, adapting to change, and working toward meaningful goals. Whether you are beginning to organize your finances or looking for ways to strengthen an established plan, small improvements can make a meaningful difference over time.
The strongest financial habits are often simple: understand where your money goes, create a realistic spending plan, maintain appropriate savings, manage debt carefully, learn before making major financial decisions, and keep your long-term goals in view.
With patience and consistency, financial planning can become less overwhelming and more empowering. The purpose is not to achieve financial perfection, but to build greater stability, flexibility, and confidence as your circumstances and goals evolve.