Managing money today can feel very different from the way previous generations handled their finances.
Digital payments, online shopping, subscription services, mobile banking, flexible work arrangements, and easy access to financial information have created new opportunities as well as new challenges.
With so many choices available, practical personal finance is less about following complicated rules and more about developing simple habits that fit your everyday life.
A strong financial routine begins with understanding where your money comes from and where it goes. Many people know their monthly income but have only a general idea of their total spending. Reviewing your regular expenses can provide a clearer picture of your financial situation. Housing, transportation, groceries, utilities, entertainment, subscriptions, and occasional purchases can all add up. When you understand these patterns, it becomes easier to make thoughtful decisions without feeling restricted.
Creating a realistic spending plan is one of the most useful steps you can take. A good plan does not require you to eliminate everything you enjoy. Instead, it helps you decide how much money should be directed toward essential expenses, personal priorities, savings, and flexible spending. Your plan should reflect your actual lifestyle rather than an idealized version of how you think you should live.
Technology can make this process easier. Banking applications and budgeting tools can help you monitor transactions and identify recurring expenses. However, convenience should not replace awareness. Automatic payments can be useful, but they can also make it easy to forget about services you no longer use. Reviewing subscriptions and recurring charges from time to time can help keep your spending aligned with your current needs.
Saving is another important part of modern financial planning. You do not necessarily need a large amount of money to begin. Consistency can be more important than starting with a significant balance. Setting aside a manageable amount after receiving income can gradually build a financial cushion. If your income changes from month to month, you can adjust the amount you save according to your circumstances.
An emergency fund can provide additional flexibility when unexpected costs appear. Car repairs, household expenses, temporary changes in income, or other surprises can place pressure on a household budget. Having money reserved for these situations can reduce the need to rely immediately on credit. The appropriate amount depends on your personal circumstances, income stability, and regular expenses, so building your reserve gradually can be a practical approach.
Debt also deserves careful attention. Not all borrowing works the same way, and understanding the interest rate, repayment schedule, fees, and total cost can help you make better decisions. When managing existing debt, knowing exactly what you owe is an important first step. You can then evaluate your repayment priorities and consider how additional payments might affect your overall financial position.
Credit can be useful when managed responsibly. Building a positive credit history generally involves making payments on time, understanding account terms, and avoiding unnecessary borrowing. Before using credit for a purchase, consider whether the payment fits comfortably within your regular budget. A purchase may appear affordable because of a monthly payment, but looking at the full cost can provide a more accurate perspective.
Modern living also makes it easy to spend without much reflection. Online shopping platforms, digital advertising, food delivery services, and one-click purchases can reduce the time between wanting something and paying for it. Creating a small pause before nonessential purchases can help you decide whether the item supports your priorities. This does not mean avoiding enjoyable purchases. It means making them intentionally.
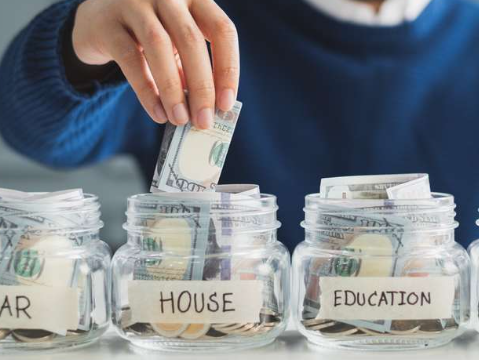
Financial goals can give your money a clear purpose. Your goals might include building savings, preparing for education, purchasing a home, starting a business, planning a trip, or simply creating greater financial flexibility. Try to make goals specific and realistic. Instead of saying that you want to save more, decide what you are saving for and establish a target that can be reviewed over time.
Long-term planning is equally important. Retirement and other future goals may seem far away, particularly when you are focused on today’s expenses. Starting early can give your savings more time to grow through the effects of compound growth. If workplace retirement plans or other suitable long-term savings options are available to you, learning how they work can help you make informed choices.
Investing can also become part of a long-term financial strategy, but it is important to approach it with realistic expectations. Investments involve risk, and values can rise and fall. Before investing, consider your goals, time horizon, financial situation, and comfort with potential losses. Diversification and a long-term perspective can be useful concepts to understand, while promises of quick or guaranteed profits should be approached cautiously.
Protecting your financial information is another essential part of modern money management. Online banking and digital payments are convenient, but they require attention to security. Use strong, unique passwords, enable available security features, and be cautious with unexpected messages requesting financial information. Regularly reviewing account activity can also help you recognize transactions that you do not remember making.
Financial planning should also leave room for life to change. Income can increase or decrease, family circumstances can shift, and priorities can evolve. A budget that worked perfectly last year may not be appropriate today. Reviewing your financial plan periodically allows you to make adjustments before small changes become larger problems.
Perhaps the most important principle of practical personal finance is to focus on progress rather than perfection. You do not need to make every financial decision perfectly. Small improvements can become meaningful when they are repeated consistently. Spending with intention, saving regularly, managing debt carefully, and learning about financial options can gradually create a stronger foundation.
Modern personal finance is ultimately about making your money work in a way that supports your life. By staying aware of your spending, planning for both expected and unexpected expenses, protecting your financial information, and setting realistic goals, you can build greater confidence in your financial decisions. The goal is not to make money management complicated. It is to create practical habits that help you live comfortably today while preparing thoughtfully for tomorrow.