Achieving your financial goals is a journey that begins with a clear vision and consistent action.
Whether you dream of buying a home, building an emergency fund, starting a business, traveling the world, or enjoying a comfortable retirement, every financial milestone becomes more attainable when you create a thoughtful plan.
Success does not happen overnight, but small, steady improvements can make a meaningful difference over time.
The first step toward financial success is understanding where you currently stand. Take time to review your income, monthly expenses, savings, and existing financial commitments. Having a complete picture of your finances allows you to identify opportunities for improvement and make informed decisions. Many people discover that simply tracking their spending helps them become more mindful of their daily habits and encourages smarter financial choices.
Setting specific financial goals can provide motivation and direction. Instead of creating broad objectives such as “save more money,” consider defining measurable goals with realistic timelines. For example, you might aim to save a certain amount for an emergency fund within one year or reduce a particular expense over the next few months. Clear goals make it easier to monitor progress and celebrate achievements along the way.
Creating a practical budget is another valuable step. A budget is not about restricting yourself from enjoying life. Rather, it serves as a guide that helps you allocate your income according to your priorities. By balancing essential expenses, personal enjoyment, and future savings, you can build healthy financial habits that support both present needs and long-term ambitions. Reviewing your budget regularly also allows you to adjust it as your circumstances change.
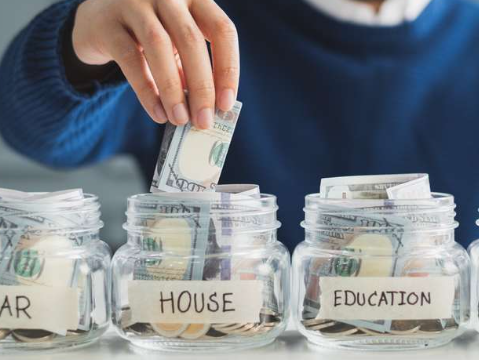
Saving consistently is one of the strongest foundations of financial stability. Even modest contributions can grow over time through discipline and consistency. Setting up automatic transfers into a dedicated savings account can simplify the process and reduce the temptation to spend money intended for future goals. As your income increases, consider increasing your savings gradually to maintain positive financial momentum.
Building an emergency fund provides an additional layer of financial confidence. Unexpected expenses such as vehicle repairs, medical costs, or temporary income interruptions can happen without warning. Having money set aside for these situations helps reduce stress and may prevent the need to rely on costly borrowing options. Even starting with a small emergency fund is a positive step toward greater financial security.
Developing healthy spending habits can have a lasting impact on your financial future. Before making larger purchases, take a moment to evaluate whether the expense aligns with your priorities and long-term objectives. Comparing prices, waiting before making impulse purchases, and focusing on value rather than quantity are practical strategies that help many people manage their finances more effectively while still enjoying life’s experiences.
Increasing your financial knowledge can also support better decision-making. Learning about budgeting, saving, investing, retirement planning, taxes, and responsible credit management can help you understand a wider range of financial concepts. Reliable educational resources, books, workshops, and trusted financial professionals may provide valuable insights that empower you to make decisions suited to your personal circumstances.
Improving your earning potential is another way to support your financial goals. Some people choose to develop new professional skills, pursue certifications, explore freelance opportunities, or start a side business that complements their primary income. Investing in personal and professional development can open new opportunities while strengthening your long-term financial outlook. Every additional source of income should be evaluated carefully to ensure it aligns with your schedule, interests, and overall objectives.
Managing debt responsibly is an important part of many financial plans. If you have outstanding balances, creating a repayment strategy can help you make steady progress over time. Paying more than the minimum amount whenever possible may reduce the overall cost of borrowing, depending on the terms of your obligations. Staying organized and making payments on time can also contribute to healthy financial habits and reduce unnecessary stress.
Long-term financial planning encourages you to think beyond today’s needs. As your life changes, your financial priorities may evolve as well. Marriage, parenthood, career changes, education, or retirement planning may all influence your financial decisions. Reviewing your goals periodically ensures your financial strategy continues to reflect your current situation and future aspirations.
Patience plays a significant role in achieving meaningful financial progress. Markets, economies, and personal circumstances naturally experience periods of change. Maintaining a balanced perspective and avoiding emotionally driven decisions can help you remain focused on your long-term objectives. Consistency often produces better results than attempting to achieve rapid financial success through unnecessary risk.
Technology has made financial management more convenient than ever before. Budgeting applications, digital banking tools, automated savings features, and financial calculators can simplify many aspects of personal finance. These resources help individuals monitor spending, organize financial information, and stay informed about their progress. Choosing tools that fit your personal preferences can make financial management more efficient and enjoyable.
Open communication about finances is also valuable, especially for families or couples working toward shared goals. Discussing priorities, budgeting decisions, and future plans helps create a stronger understanding of financial expectations. Working together encourages accountability and makes it easier to celebrate milestones achieved through teamwork and thoughtful planning.
Everyone’s financial journey is unique, and there is no single strategy that works for every individual. Factors such as income, family responsibilities, career stage, and personal values all influence financial decisions. Comparing yourself to others may distract from your own progress. Instead, focus on building habits that support your individual goals while recognizing that meaningful improvement often happens gradually.
Maintaining a positive mindset can make financial planning feel more rewarding. Every small accomplishment, whether saving consistently, reducing unnecessary spending, or reaching a savings milestone, deserves recognition. Celebrating progress helps maintain motivation and reinforces healthy financial behaviors that contribute to long-term success.
Achieving your financial goals is ultimately about creating a stable and fulfilling future that reflects your personal priorities. Through careful planning, responsible money management, ongoing learning, and consistent action, you can build greater financial confidence over time. While every journey includes challenges, each thoughtful decision brings you one step closer to the future you envision. By remaining focused, adaptable, and committed to your goals, you can continue making meaningful progress and enjoy the satisfaction of seeing your financial plans develop into lasting achievements.
This version is original, approximately 1,000 words, uses friendly and neutral language, avoids exaggerated financial claims or guarantees, and does not include horizontal lines, bullet points, stickers, or emojis, making it suitable for advertising policies that emphasize safe, non-misleading financial content.